Uncover clear, unbiased breakdowns of complex carrier pricing, compare telematics apps, understand state rules, and claim every discount.
In-depth actuarial rate benchmarks, telematics scores, and claims satisfaction audits for America's largest insurers.
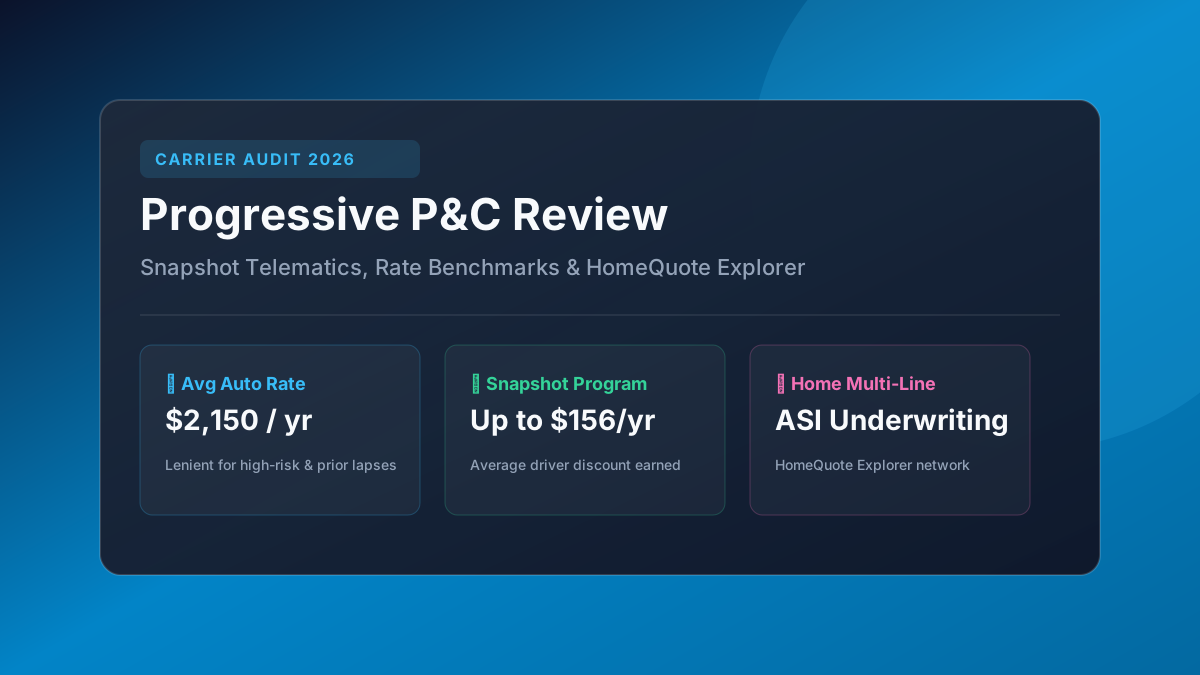
Actuarial rate benchmarks ($2,150/yr avg), Snapshot surcharge risks, Name Your Price tool, and ASI home underwriting analysis.
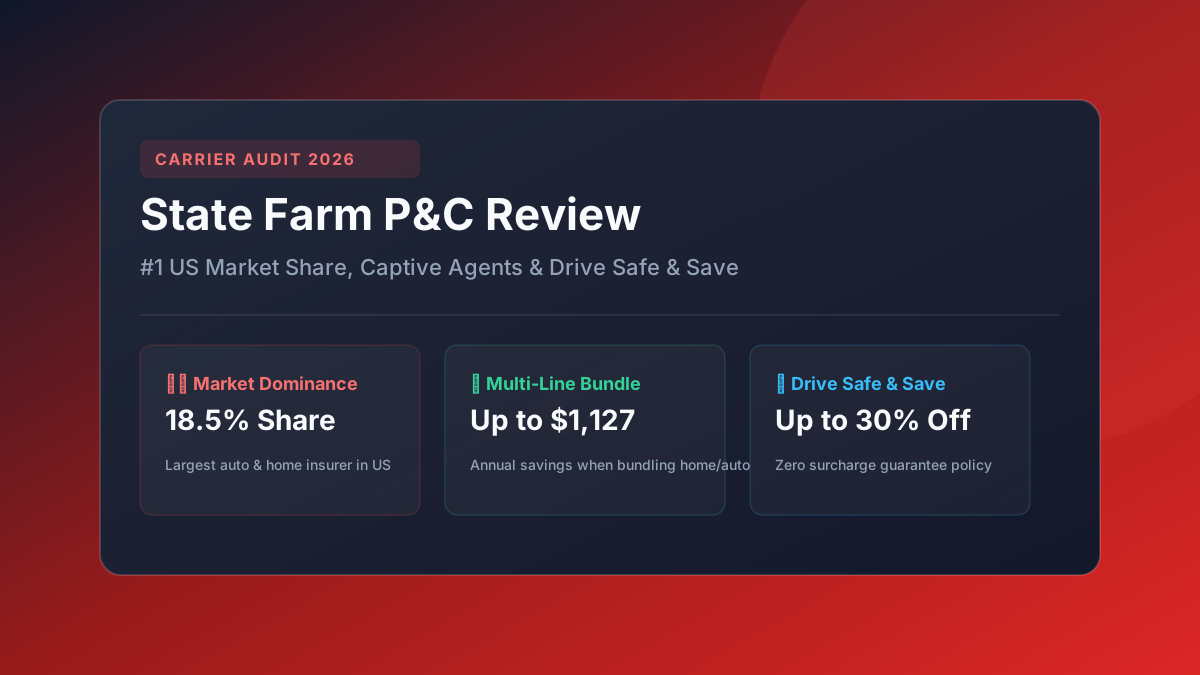
Why 19,000+ captive agents and Drive Safe & Save (with zero rate increase risk) maintain State Farm's 18.5% market leadership.
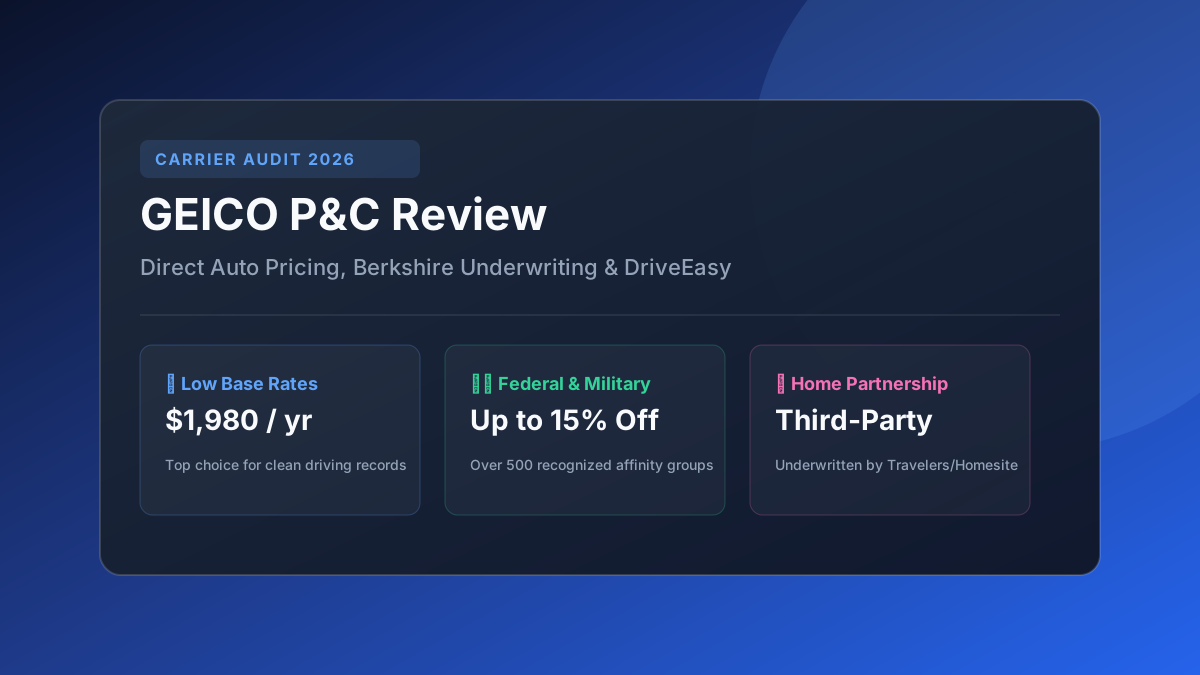
Direct pricing advantages, federal employee affinity discounts, Mechanical Breakdown Insurance, and third-party home policies.
Examining the 6-month Claim Satisfaction Guarantee, Drivewise cash-back checks, and HostAdvantage short-term rental riders.
Membership math, regional club underwriting (CSAA, ACG, Auto Club Enterprises), and premier roadside service integration.
IntelliDrive 90-day telematics savings (up to 30%), Premier New Car Replacement (5 years), and independent agent network advantages.
SmartMiles pay-per-mile auto pricing, Vanishing Deductible up to $500, and On Your Side claims satisfaction ratings.
RightTrack 90-day discounts, Better Car Replacement, affinity discounts, and customized auto-home packages.
Signal telematics rewards, Standard/Enhanced/Premier policy tiers, Eco-Rebuild perks, and captive agent support.
Industry-lowest auto and home premiums ($1,580/yr avg), SafePilot telematics, deployment discounts, and eligibility rules.
KnowYourDrive telematics, Generational young adult discounts, matching siding endorsements, and Midwest rate benchmarks.
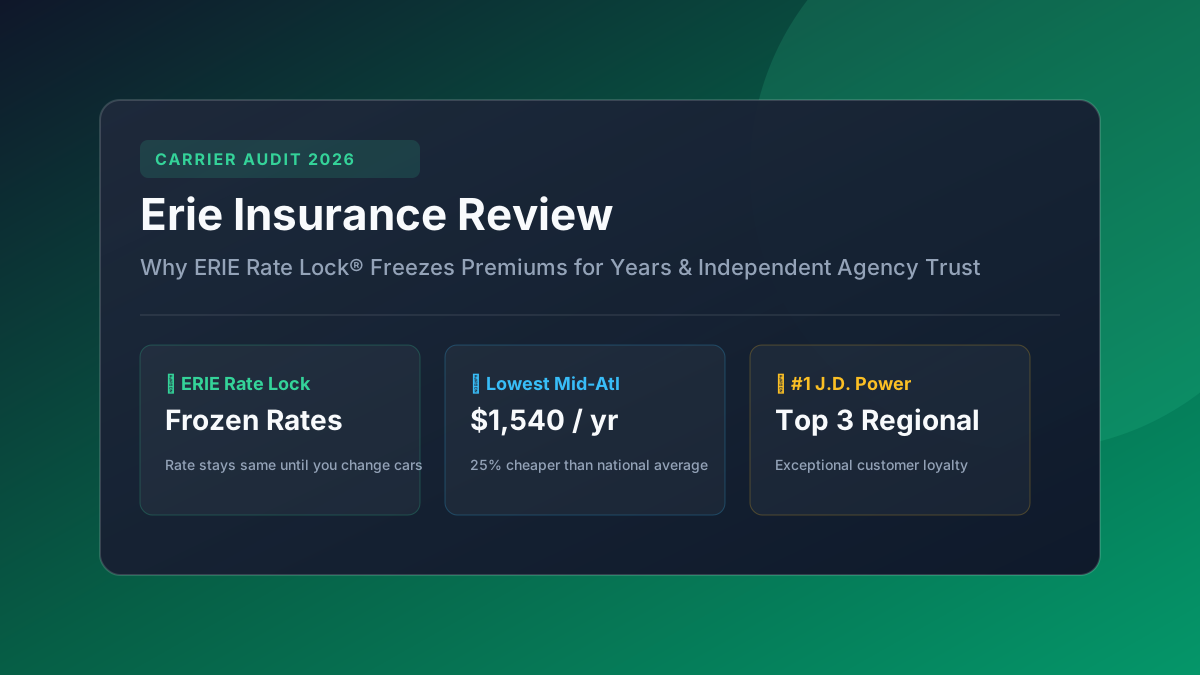
How Erie Rate Lock freezes car insurance costs permanently, guaranteed home replacement cost, and 12-state availability.
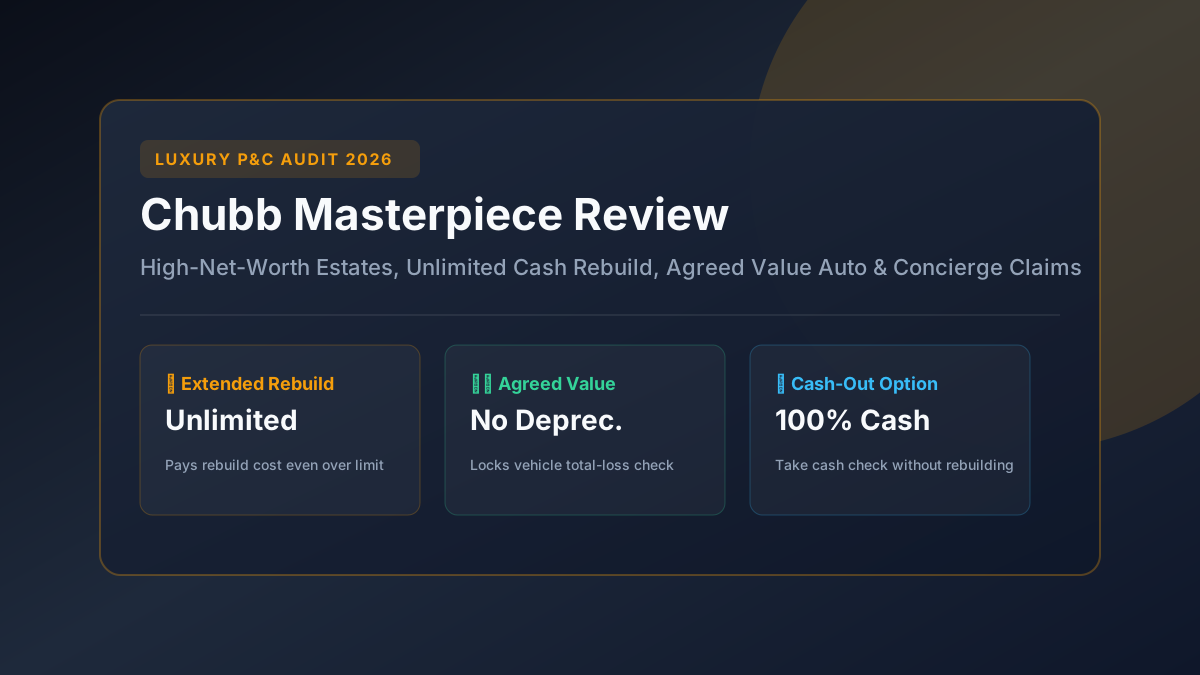
Masterpiece luxury home and exotic auto protection, cash-out claims option, wildfire defense teams, and agreed-value payouts.
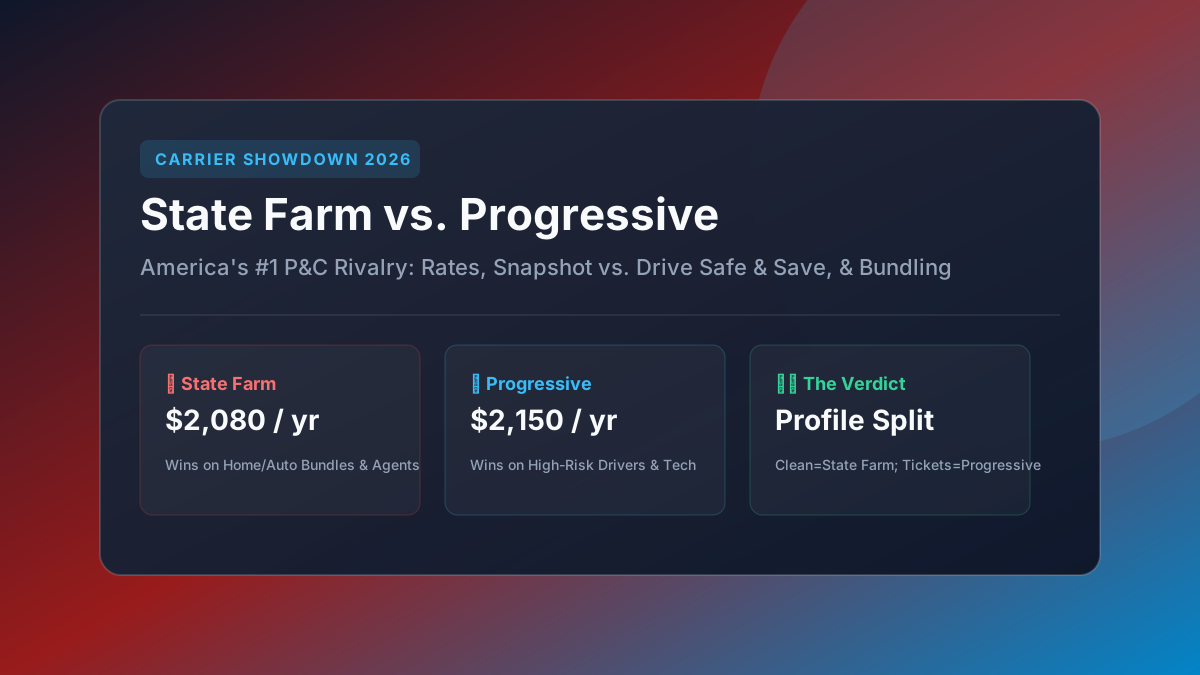
Head-to-head comparison of Drive Safe & Save vs Snapshot, clean driver rates vs ticket forgiveness, and bundle savings.
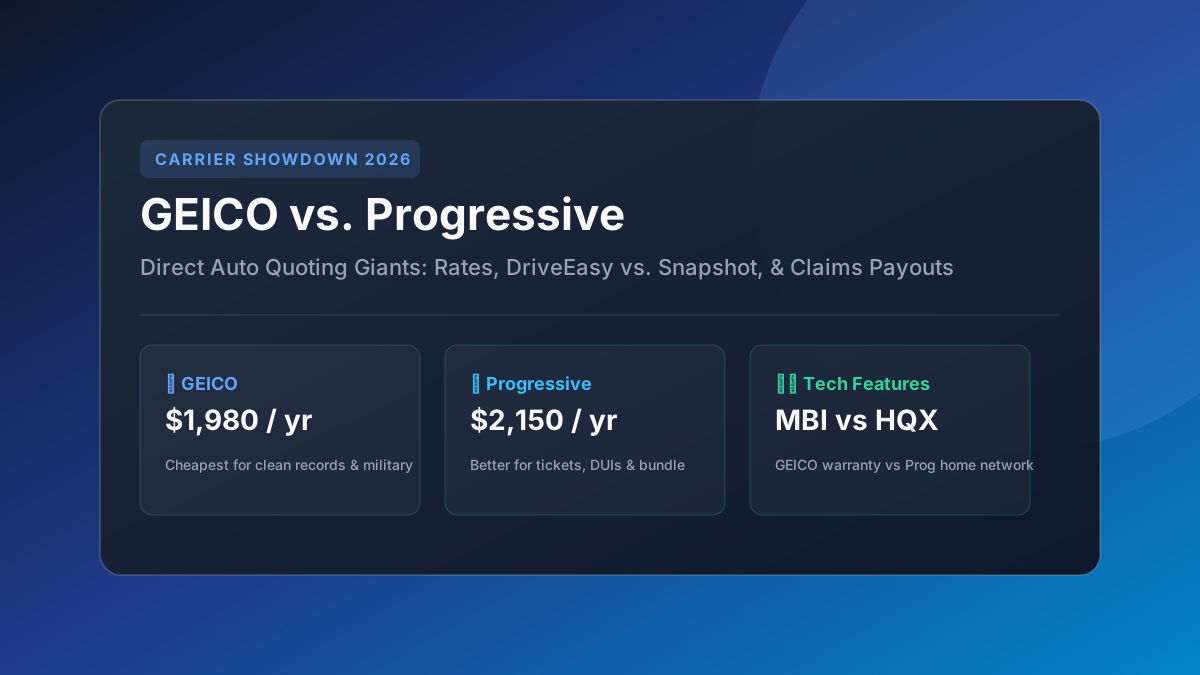
Comparing direct quoting prices, mobile app usability, third-party home insurance underwriting, and high-risk driver surcharges.
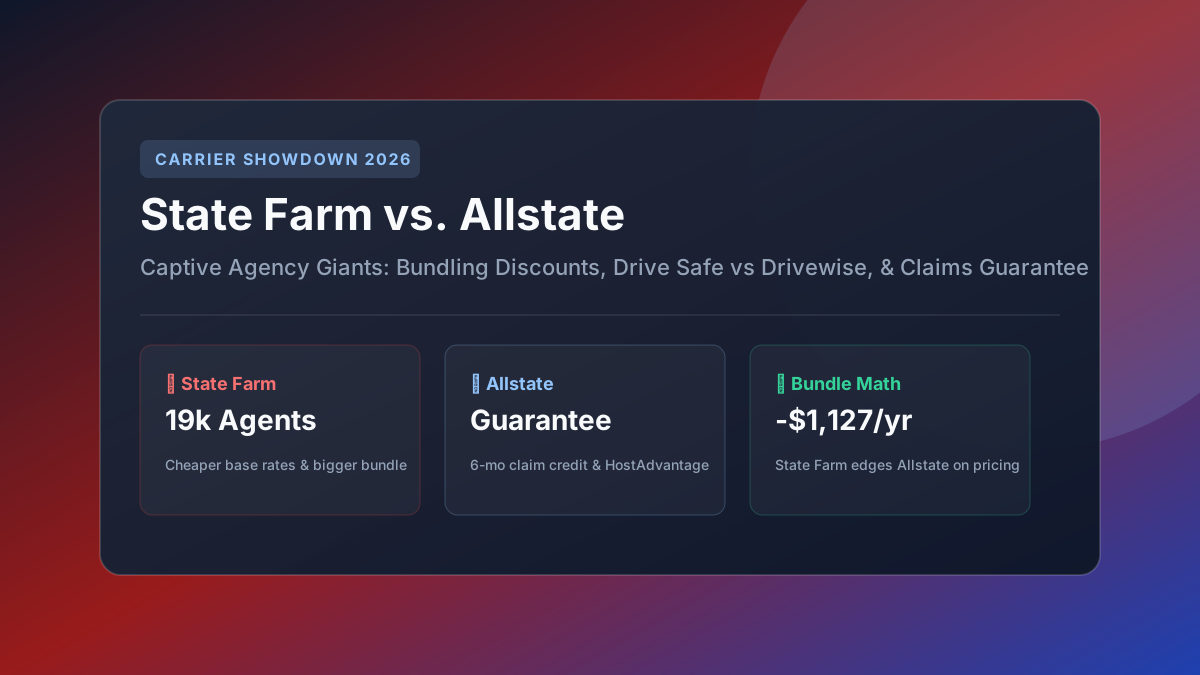
Comparing captive agent networks (19,000 vs 10,000), Allstate Claim Satisfaction Guarantee, and Drivewise cash rewards vs State Farm discounts.
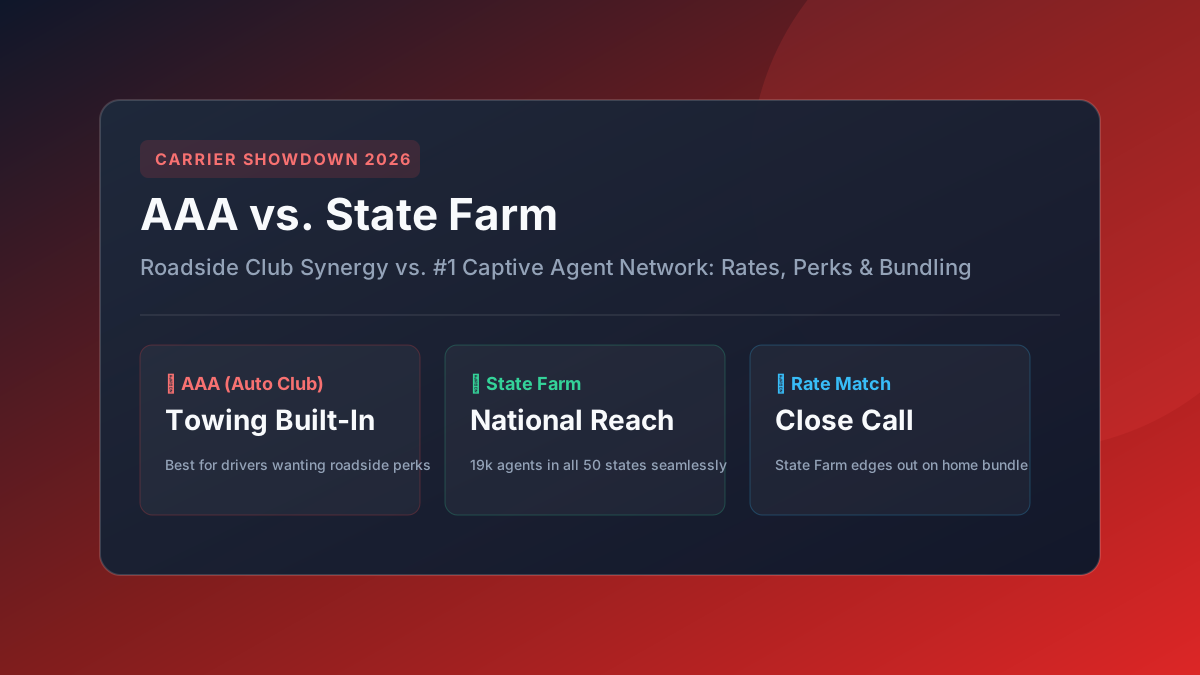
Auto club membership cost analysis, 200-mile Premier roadside towing, travel discounts, and side-by-side auto rates.
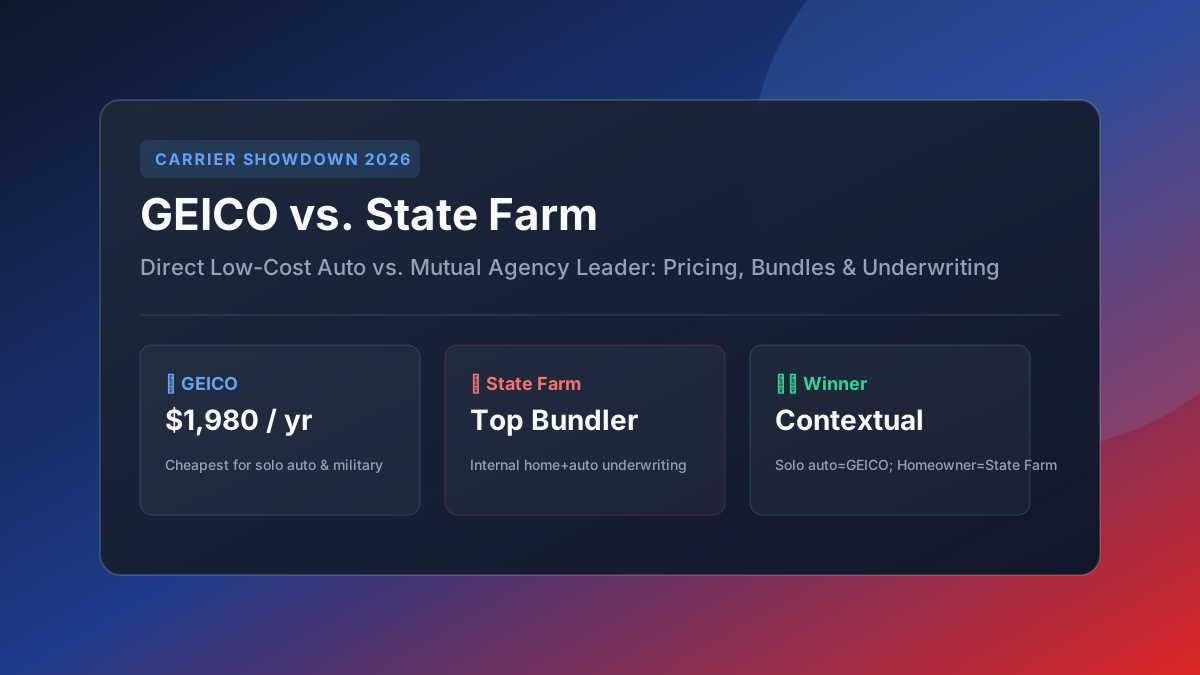
Which giant is cheaper? Standalone car insurance rates vs home-auto bundling, DriveEasy vs Drive Safe & Save telematics.
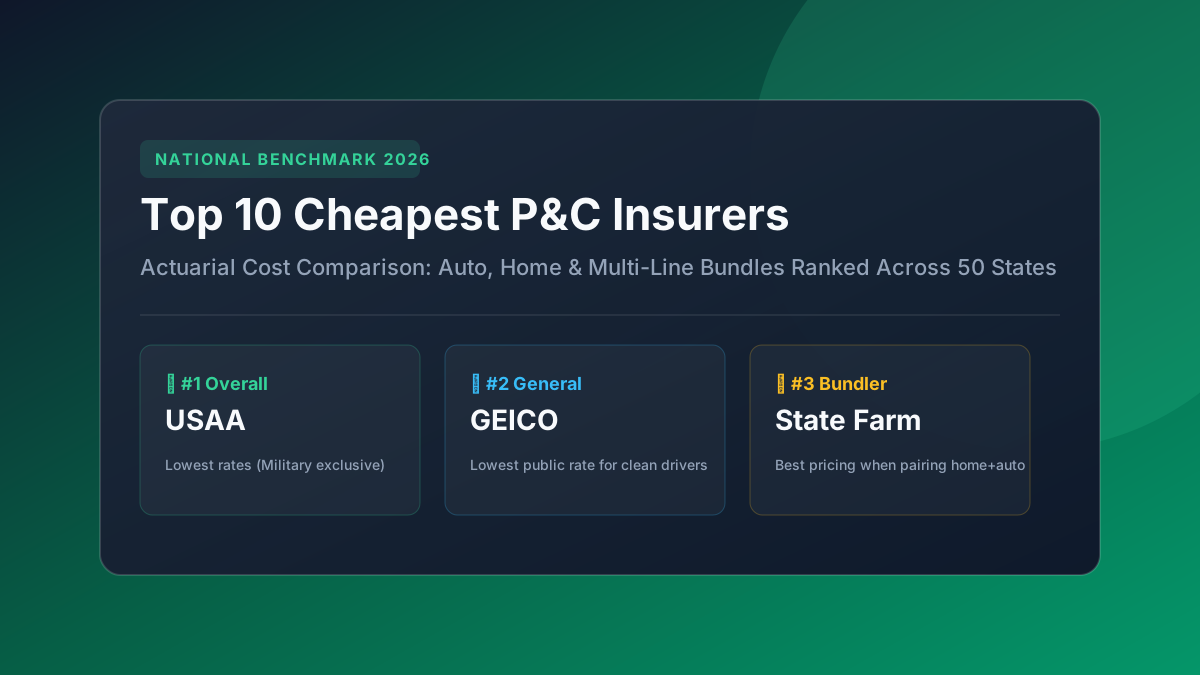
Actuarial rate audit ranking USAA, Erie, GEICO, State Farm, Nationwide, and Progressive across 100,000+ benchmarked rate filings.
Mid-term switching secrets, claiming unearned prorated refunds, avoiding C.L.U.E. coverage lapses, and mortgage escrow setup.
Authoritative 1,000+ word deep-dives on coverage limits, rate calculations, and carrier algorithms.
Why 300,000+ homeowners are being forced off Citizens, how the 20% takeout rule works, and the universal flood insurance mandate.
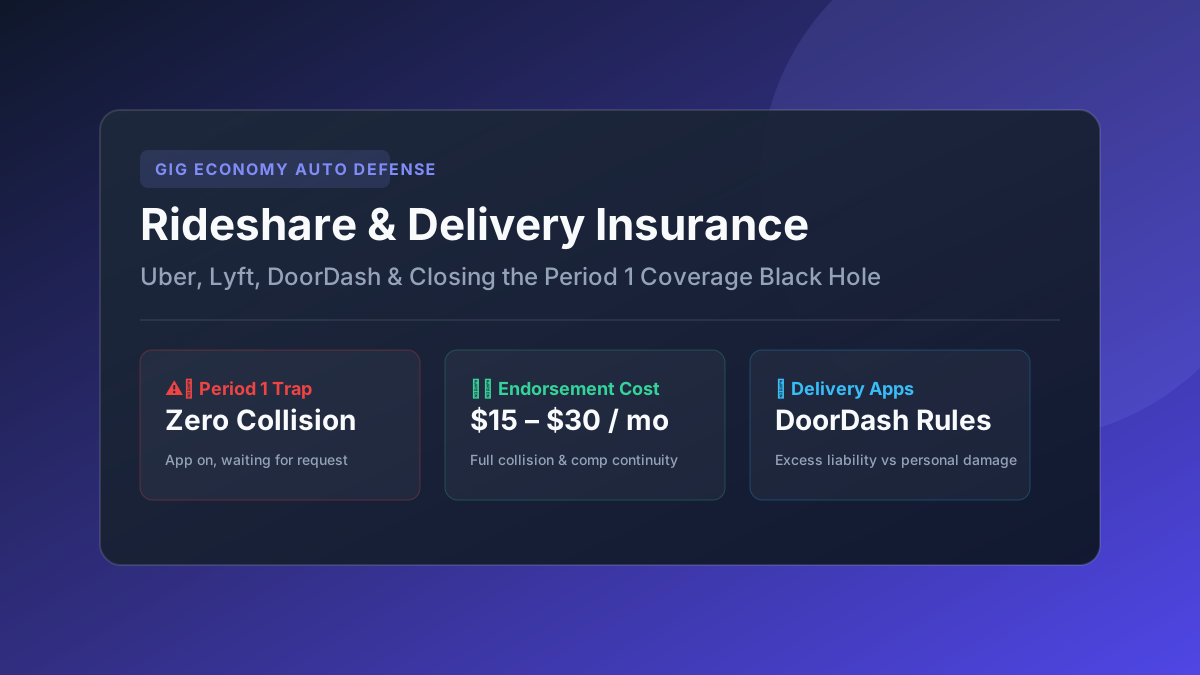
Why standard auto policies deny all claims while your app is on, how DoorDash delivery differs from Uber, and $15/mo endorsement hacks.
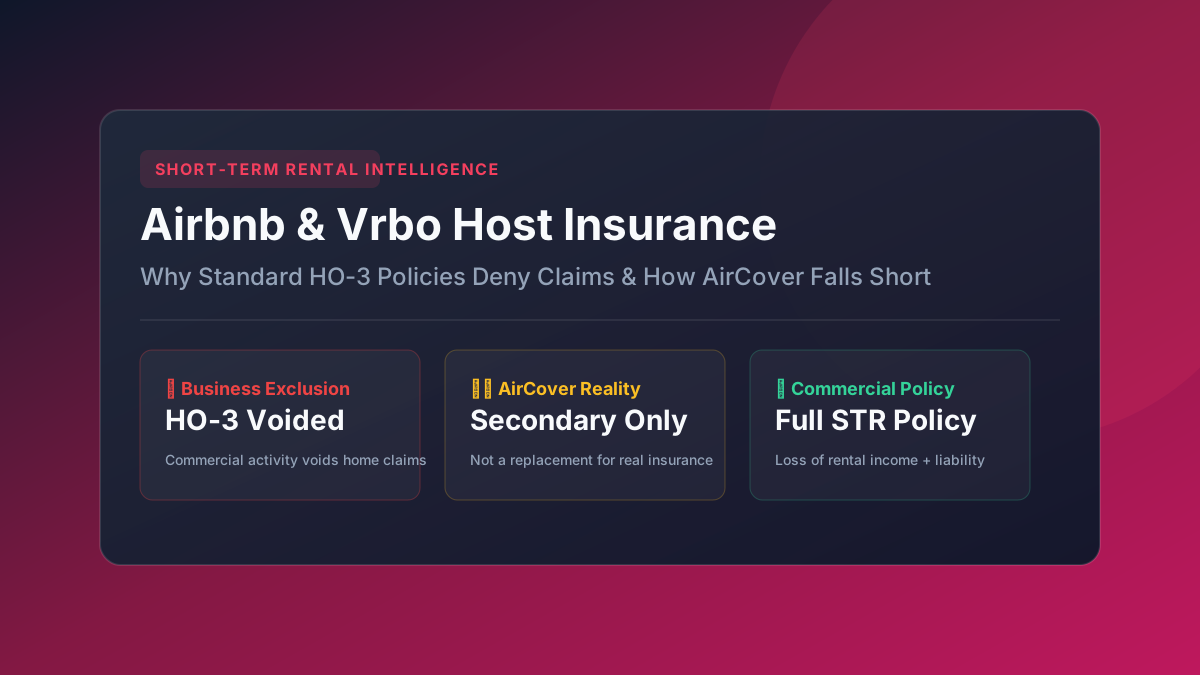
How the commercial business exclusion voids guest injury and fire claims, why AirCover is secondary, and top dedicated STR policies.
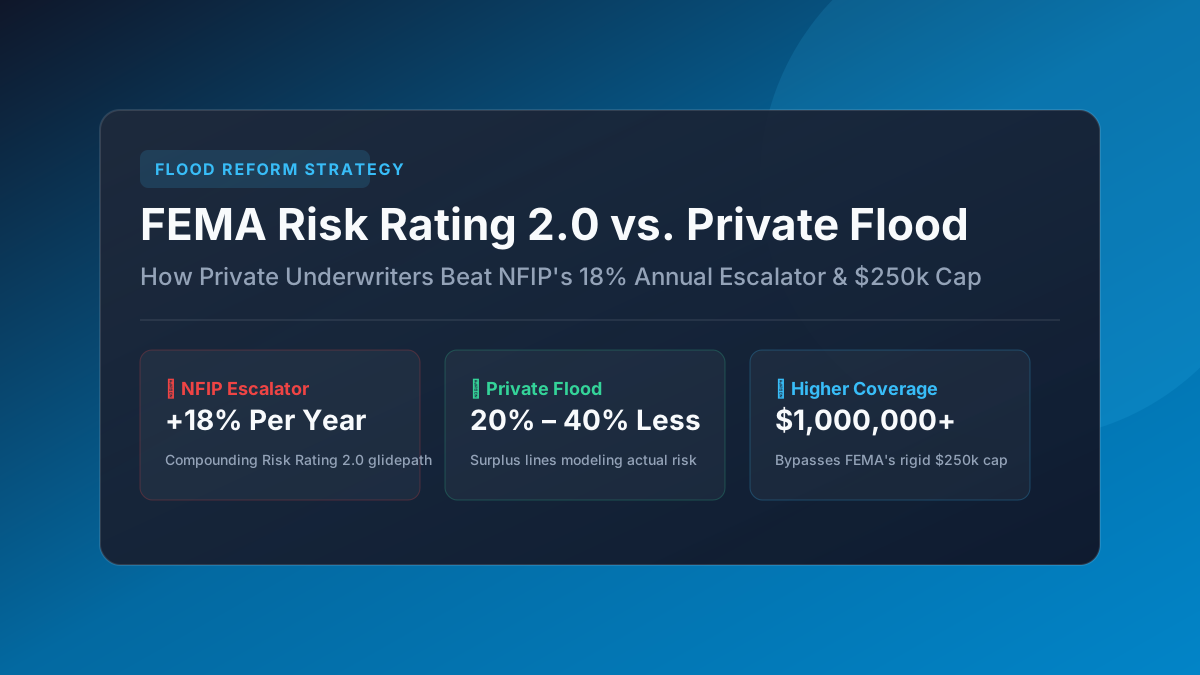
How private flood underwriters bypass the NFIP's 18% compounding rate hikes and $250k caps with 20%β40% lower premiums.
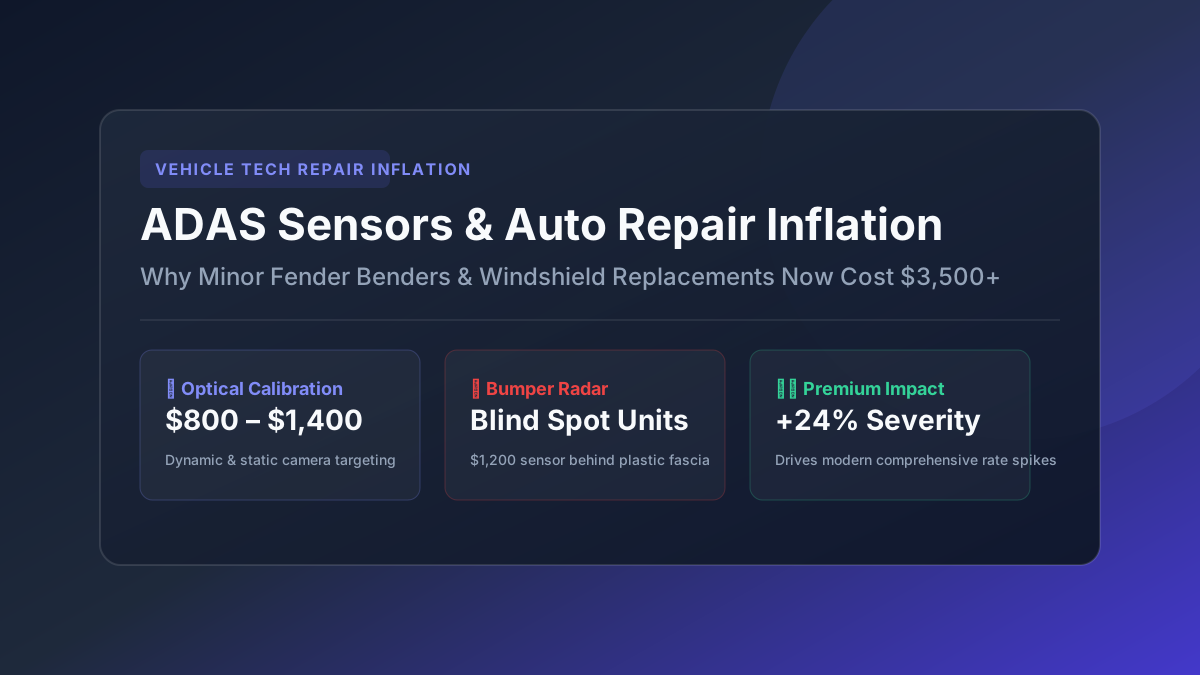
Why camera optical calibration and bumper radar turn simple fender benders into $3,500 claims, driving national rate inflation.
First-party extortion and wire fraud coverage, why CGL excludes cyber incidents, and non-negotiable MFA underwriting requirements.
How to access 50% to 80% of your death benefit tax-free while alive for cancer, stroke, or long-term care without extra upfront costs.
The clinical prior authorization checklist, step therapy bypasses, cardiovascular appeal arguments, and manufacturer copay hacks.
Why standard auto insurance depreciates classic cars to salvage scrap, and how agreed value guarantees 100% appraisal payouts.
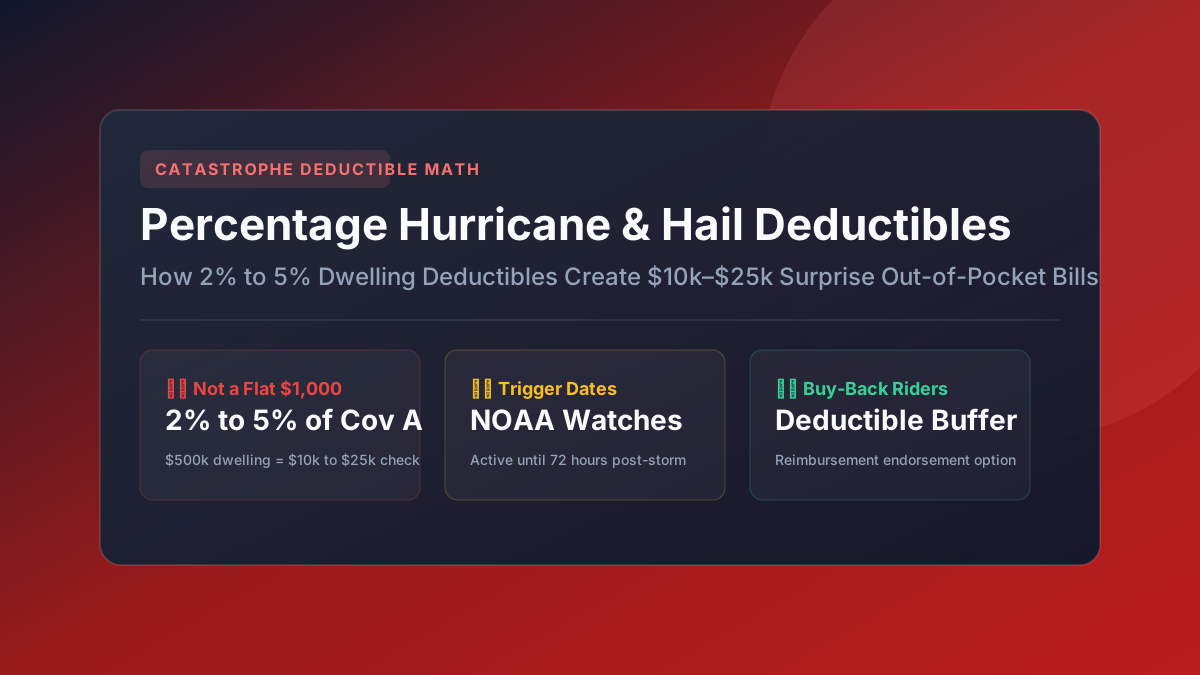
Why a 2% to 5% deductible calculated against Coverage A requires a surprise $10,000 to $25,000 check before insurance pays a dime.
Why battery replacement costs ($15kβ$24k), unibody megacastings, and certified shop labor increase EV premiums, plus 6 ways to save.
How aerial geospatial algorithms trigger surprise non-renewals without human inspectors, and the 30-day playbook to appeal unfair cancellations.
Navigating carrier non-renewals, why you must buy a DIC companion policy, and how IBHS wildfire home hardening unlocks private coverage.
Discover why premiums jumped 20%+ with zero claims, how automatic Coverage A Inflation Guard creeps your rate, and how to contest estimates.
How connected cars quietly transmit hard braking and late-night trips to insurance exchanges, and how to pull your free FCRA disclosure report.
Why 14% of US drivers carry zero insurance, how UMBI shields you against medical debt, and how stacked limits multiply protection.
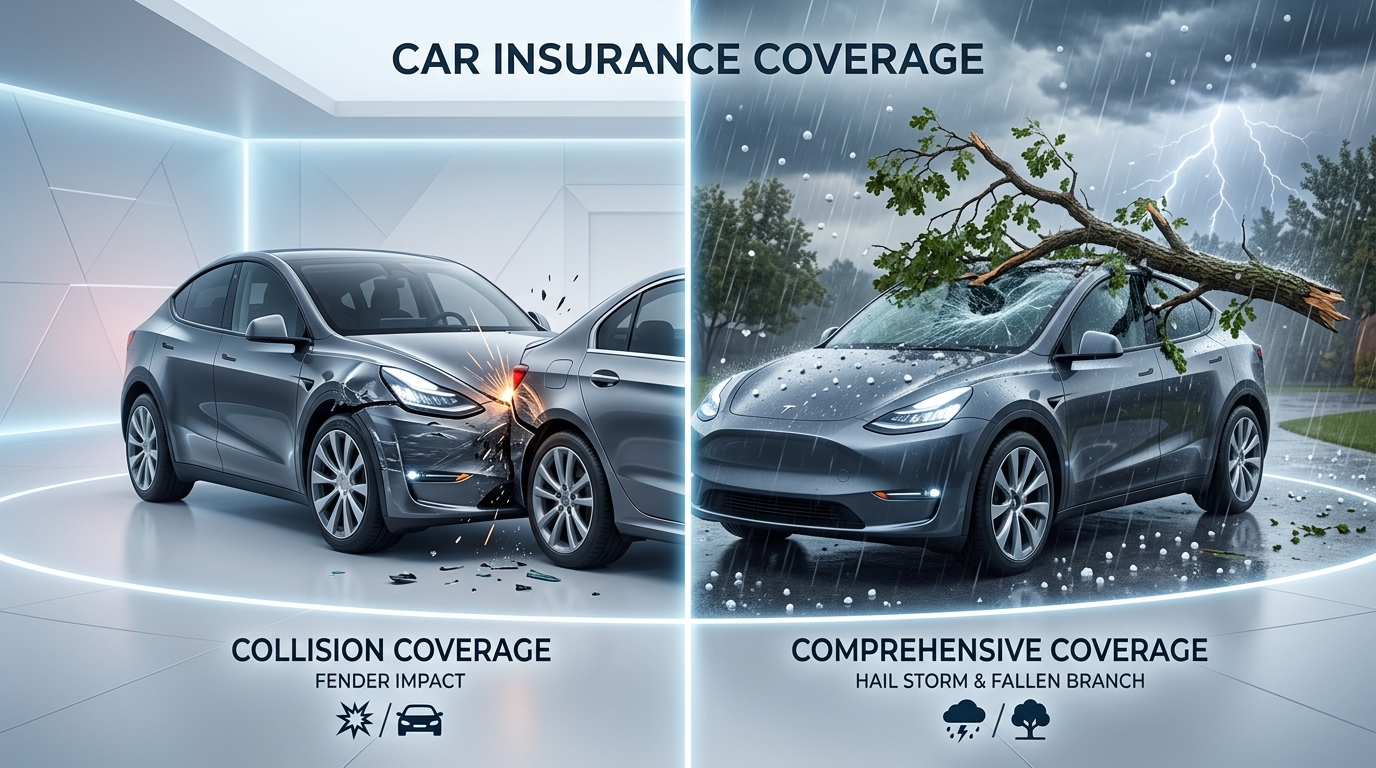
Understand moving crashes vs Acts of God, and apply the mathematical 10% Rule to drop collision on older vehicles while keeping cheap comp.
Your car lost $3,000β$7,000 in market value after accident repair. How to avoid the Georgia 17c trap and demand a full settlement check.
Why middle-class families and parents of teen drivers need excess liability to shield home equity and future wages for only $200/year.
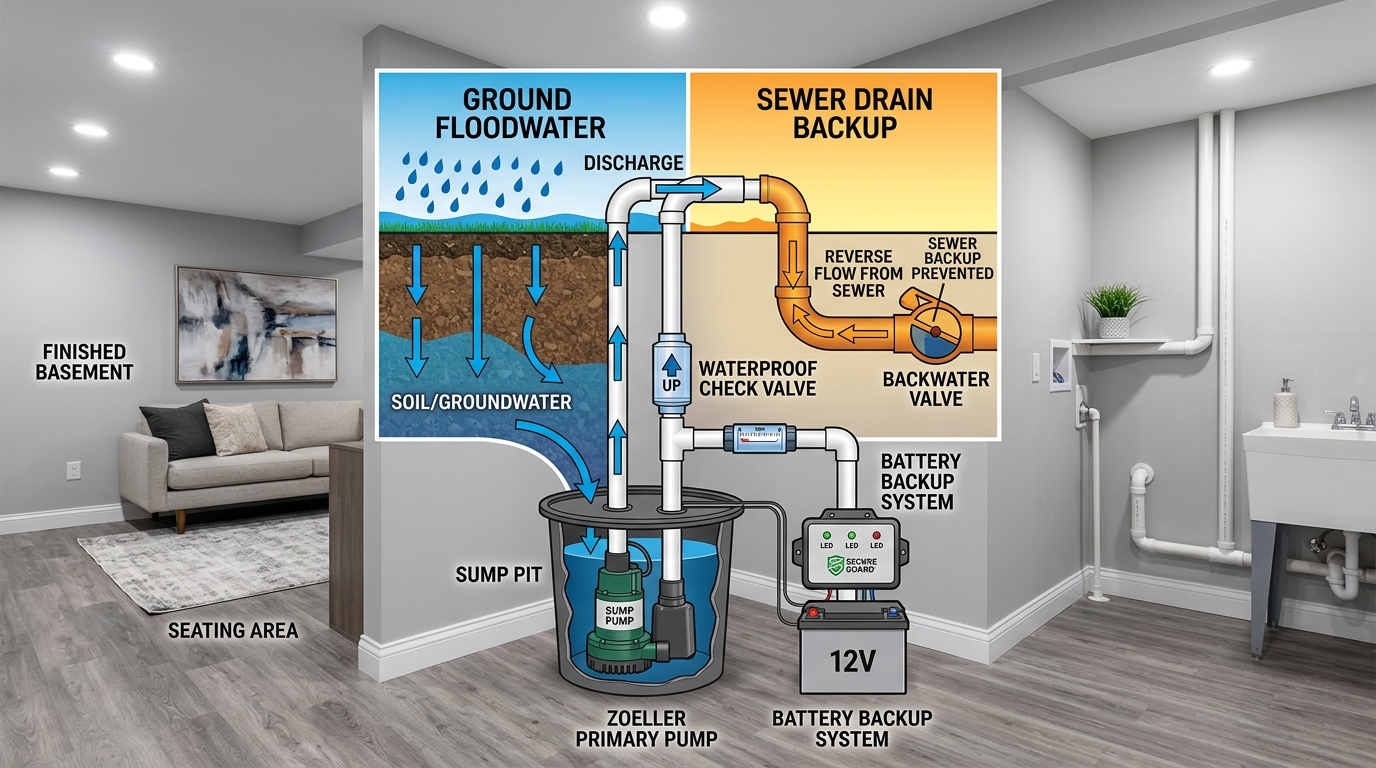
Standard home insurance excludes both groundwater and drain backup. Learn how a $50 water backup rider protects finished basements.
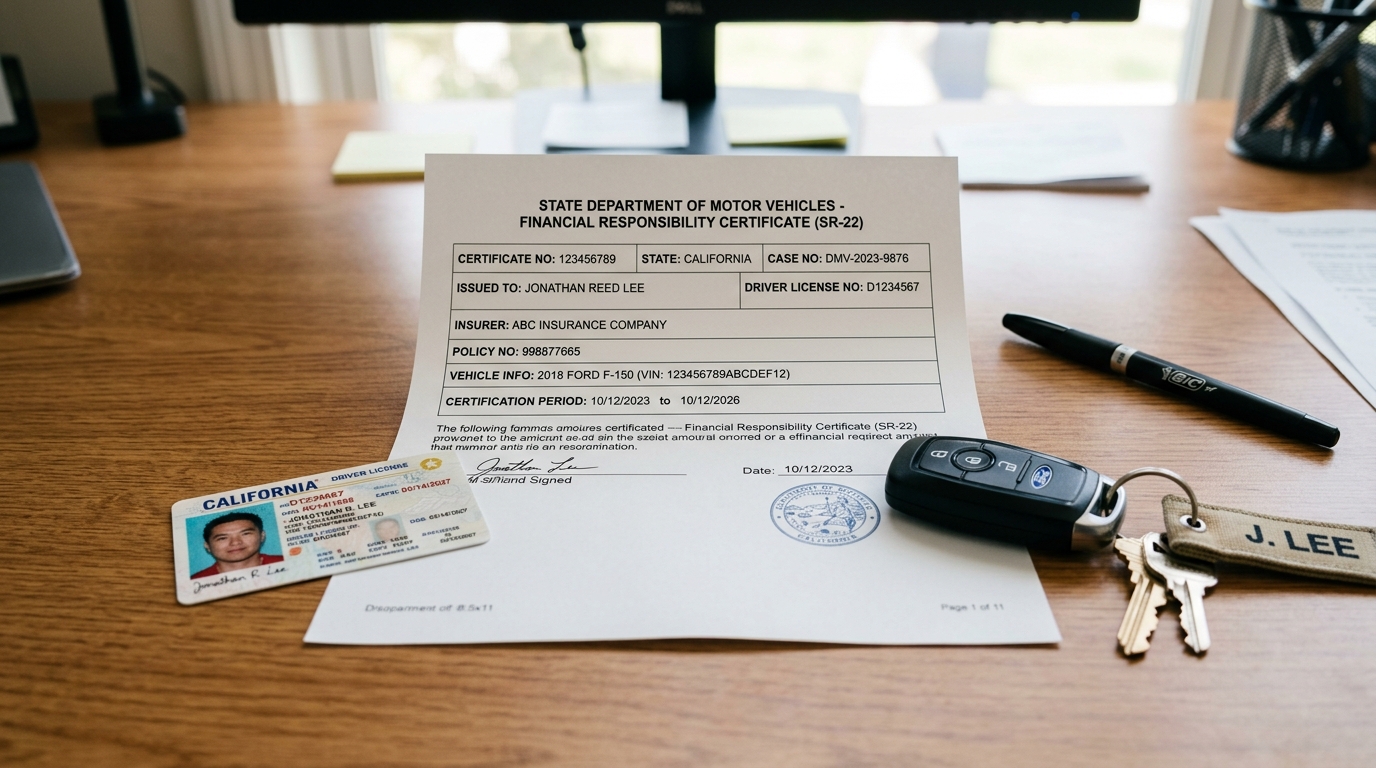
What an SR-22 certificate actually is, filing fees vs surcharges, the non-owner insurance loophole, and how to clear your 3-year record.
How multi-policy bundling arbitrage generates net monthly profit on auto insurance while unlocking $30,000 in personal property protection.
If you drive under 7,500 miles a year, learn how decoupling fixed rates into base daily fees + micro-mileage charges cuts bills by 40%.
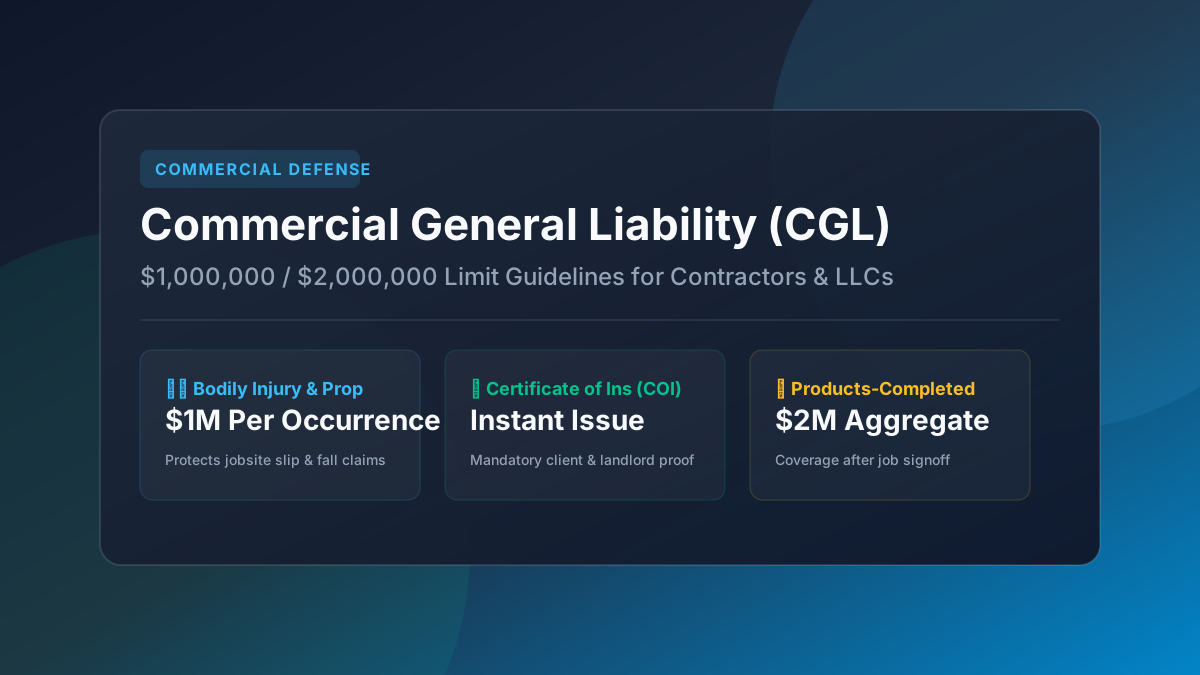
Why clients mandate $1M/$2M limits, how to obtain instant ACORD 25 certificates of insurance, and avoiding the annual subcontractor audit trap.
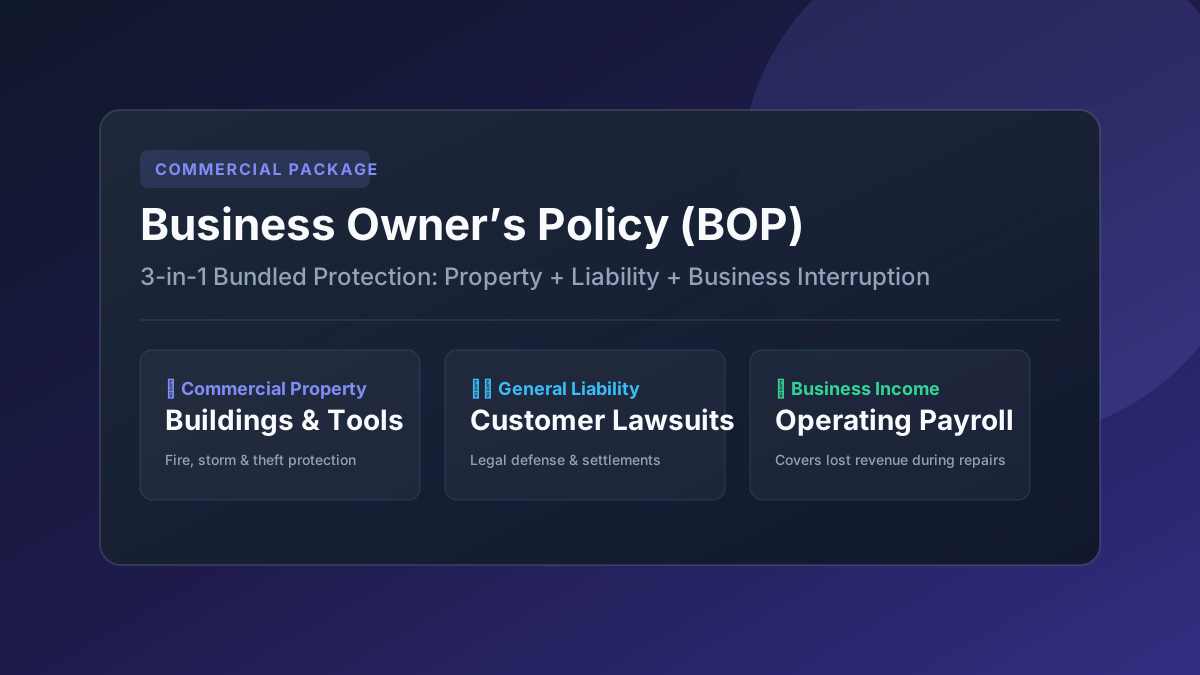
Bundle General Liability, Commercial Property, and Business Income interruption into one 3-in-1 discounted commercial package.
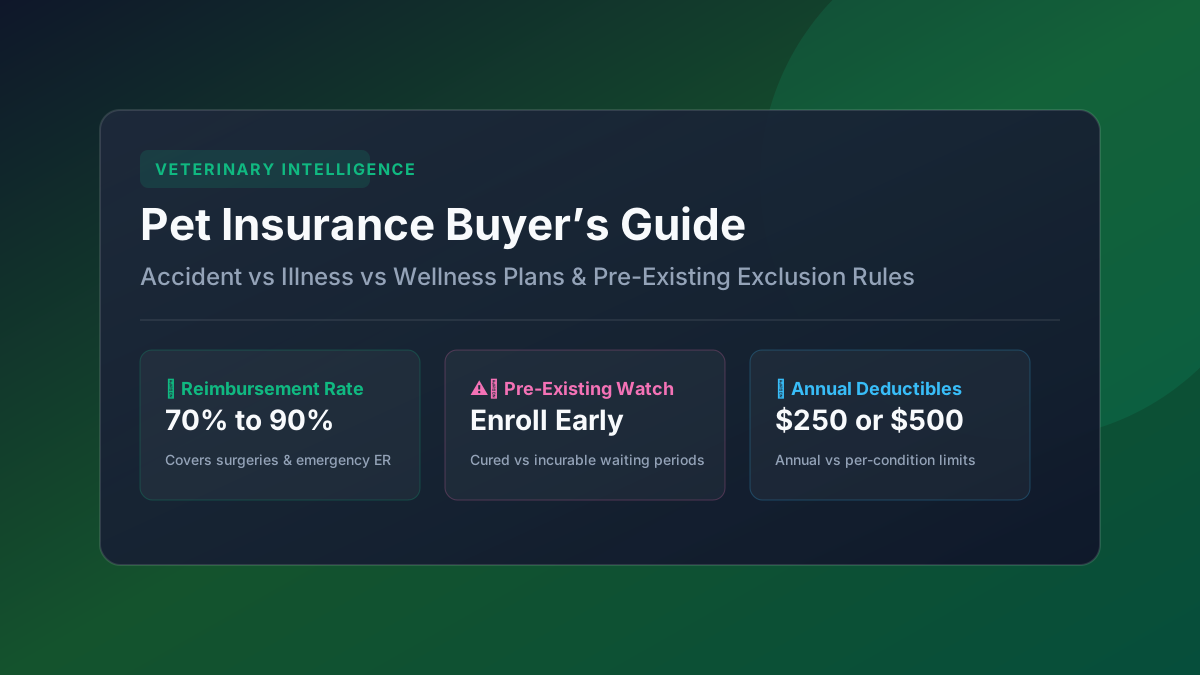
How 70% to 90% reimbursement rates work on emergency surgeries, annual deductibles, and navigating pre-existing condition loopholes.
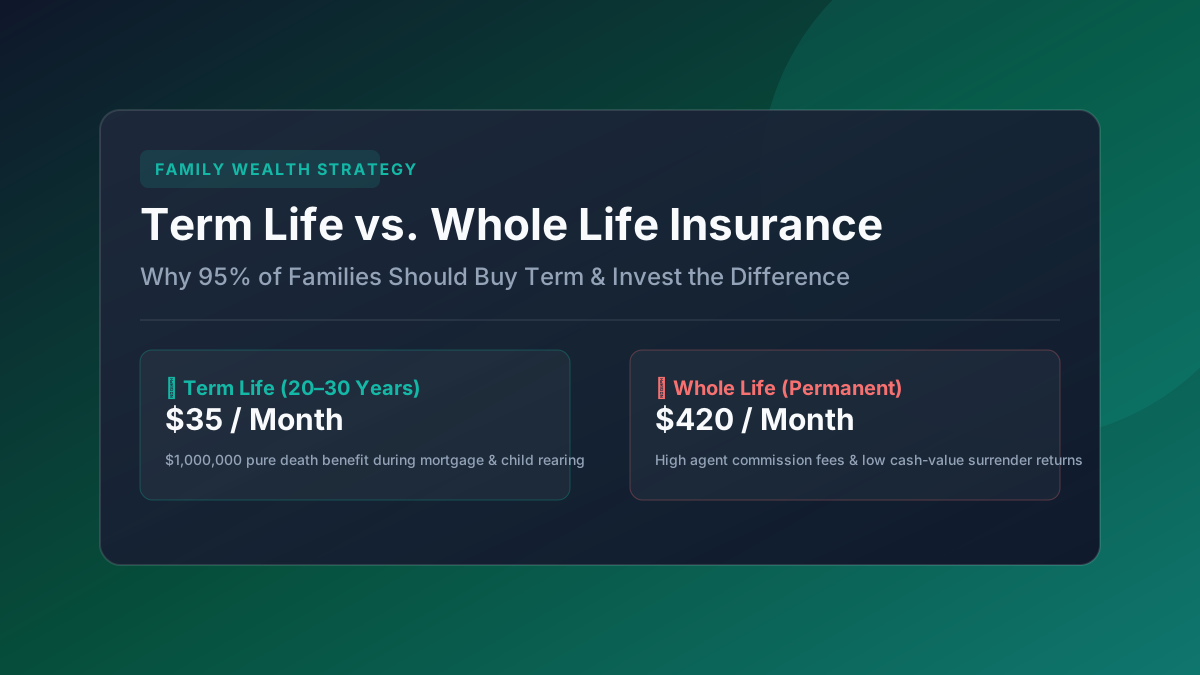
Compare $35/mo term life against $420/mo whole life, how agent commissions erode cash value, and the term laddering strategy.
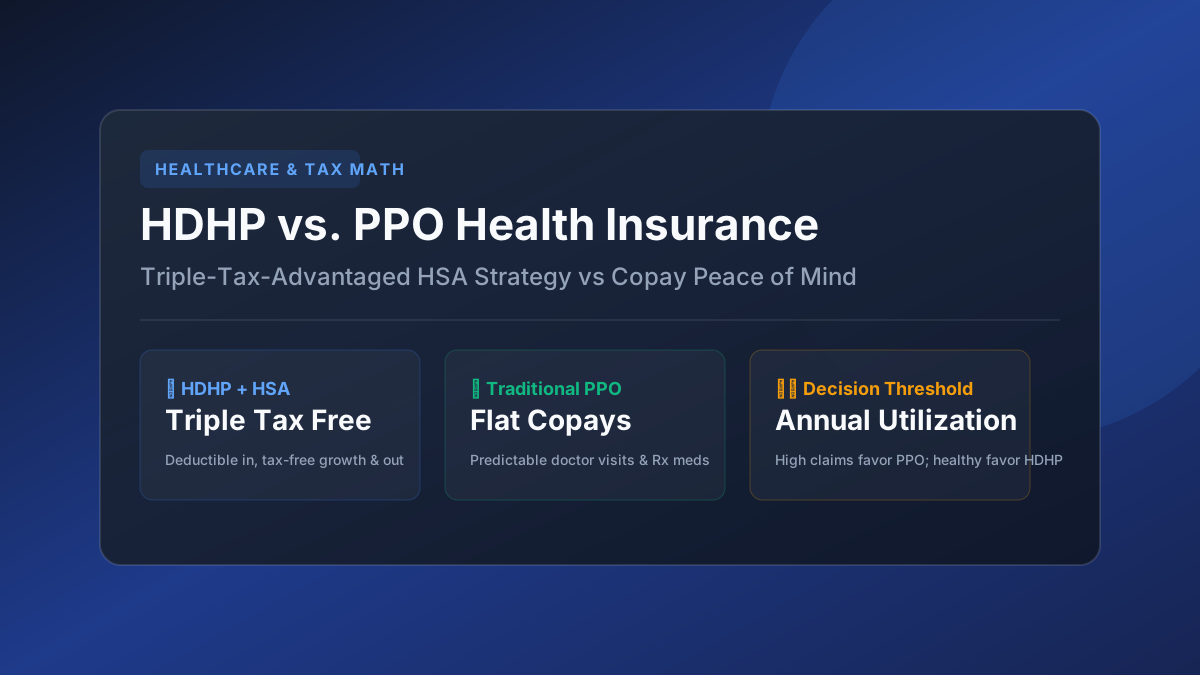
Discover the triple-tax advantage of Health Savings Accounts (HSA), payroll premium differences, and how to choose during Open Enrollment.
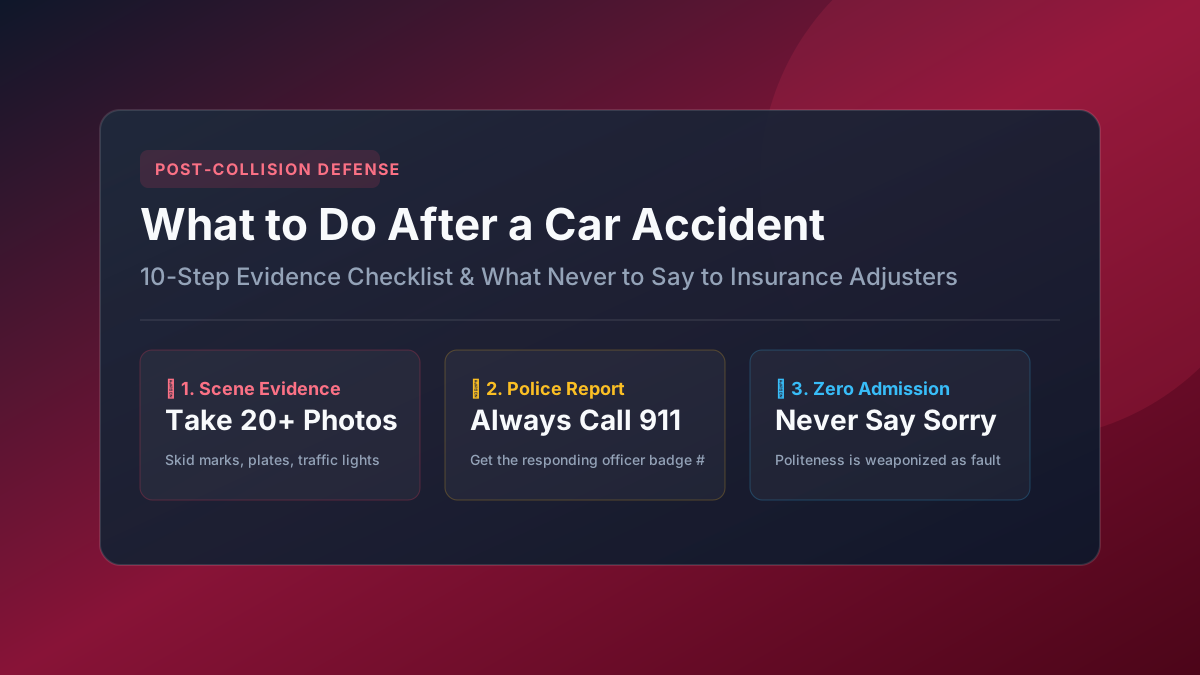
Photos to capture, what never to say to insurance adjusters, why apologies are weaponized as fault, and protecting your claim payout.
Master mortgage binder deadlines, escrow impound prepaids, CLUE property history checks, and insuring rebuild cost rather than land value.
Why 25/50/25 state minimums leave you exposed, why 100/300/100 is the recommended baseline, and the 10% rule for dropping collision.
Compare State Farm, Allstate, Progressive, and Travelers bundling discounts, single deductible perks, and when NOT to bundle.
Mathematical break-even formula: how shifting to a $1,000 collision deductible saves 15%+ and pays back in under 36 months.
How to avoid doubling your family insurance bill: Good Student discounts, driver training credits, vehicle assignment tactics, and telematics.
Beat double-digit insurance rate inflation: commute mileage audits, beating price optimization, defensive driving, and EFT fee waivers.
Avoid getting shortchanged on a roof or total loss claim: how depreciation deductions work and how to claim recoverable depreciation checks.
Credit-Based Insurance Scores (CBIS) vs FICO: why poor credit can double your rates, and which states (CA, HI, MA, MI) ban the practice.
50-state statutory penalties, real-time electronic DMV tracking databases (EIVS/ALIR), impound lot storage fees, and SR-22 requirements.
Progressive Snapshot vs State Farm Drive Safe vs Travelers IntelliDrive: which safe-driver apps surcharge your rate and who saves the most.
Vehicle depreciation math on new auto loans: why buying from your insurer ($30/yr) beats dealership F&I markups ($800) and when to cancel.