Key Takeaways at a Glance
- The Negative Net Cost Phenomenon: Adding a renters insurance policy ($12–$15/mo) unlocks a 10% to 15% multi-policy discount on your auto policy, often saving $25–$35/month.
- Landlord Policy Myth: Your apartment landlord’s commercial building insurance covers the physical walls and roof; it pays $0 if your laptop, furniture, or clothes are stolen or burned.
- Away-From-Home Property: Renters insurance protects your personal property anywhere in the world—including a laptop stolen from your locked car trunk or hotel room.
- $100,000 Liability Shield: Covers accidental damage or dog bite lawsuits inside your rental unit, preventing catastrophic personal liability judgments.
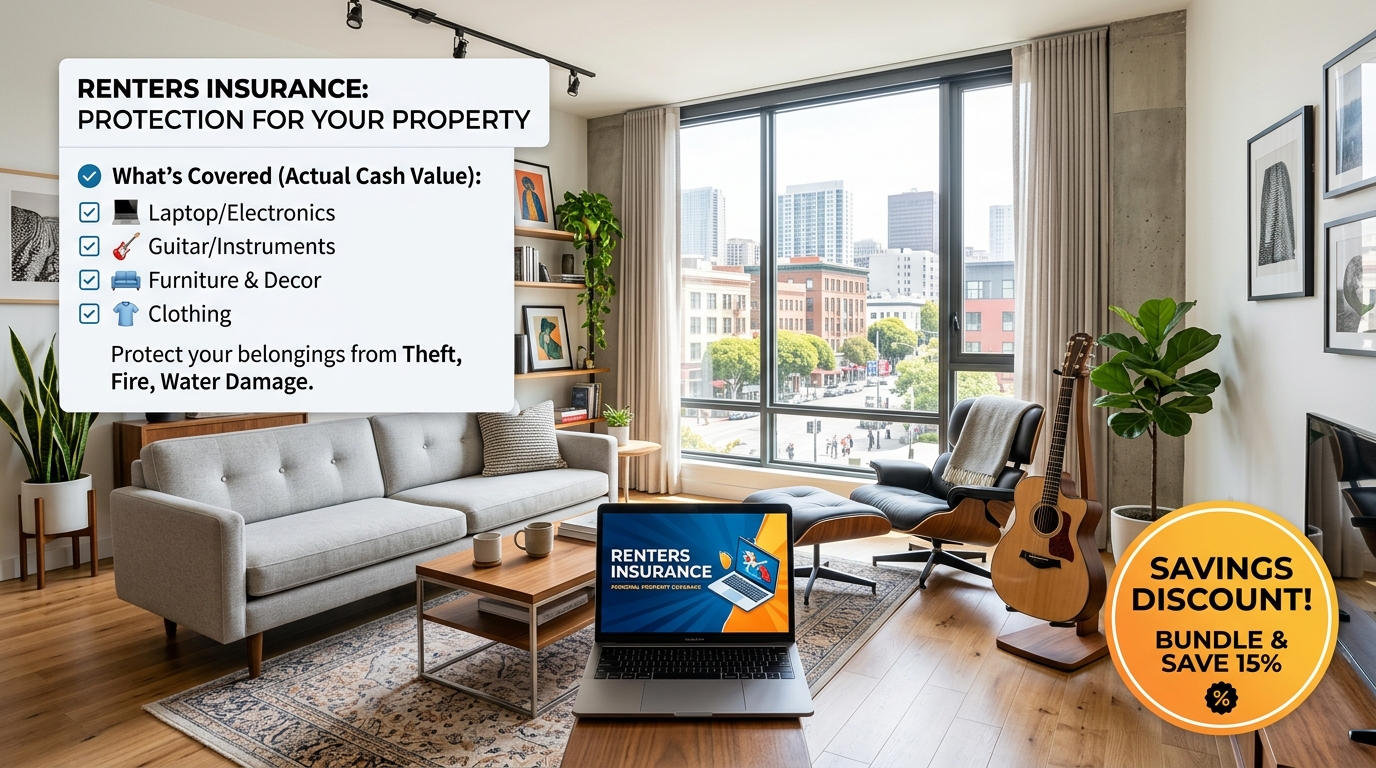
1. The Reverse Bundle Hack: Profiting from Multi-Policy Discounts
In personal finance, it is extraordinarily rare to purchase an additional product and end up with more money in your bank account every month. Yet, in Property & Casualty insurance, the "Renters Insurance Bundling Arbitrage" is one of the insurance industry’s best-kept secrets.
Insurance carriers rely heavily on customer retention metrics. Actuarial data shows that policyholders who maintain two policies with the same carrier (such as auto + renters) stay with the company 45% longer and file fewer frivolous claims than single-policy customers.
To attract and retain these profitable households, carriers offer substantial multi-policy discounts—typically between 10% and 18% off your auto insurance premium. If you pay $180 per month for car insurance, a 15% discount saves you $27 per month. Since a basic renters policy costs only $12 to $14 per month, you achieve a net cash savings of $13 to $15 every month while gaining comprehensive property and liability protection!
2. The Real-World Mathematical Breakdown
Here is the exact monthly balance sheet for an urban driver living in a rental apartment:
| Insurance Setup | Auto Monthly Bill | Renters Monthly Bill | Net Total Monthly Cost | Annual Savings |
|---|---|---|---|---|
| Standalone Auto Insurance Only | $175.00 / mo | $0.00 (Unprotected) | $175.00 / mo | $0 (Baseline) |
| Auto + Renters Policy Bundle | $148.75 / mo (-15% discount) | $12.50 / mo ($30k coverage) | $161.25 / mo | +$165.00 / yr NET PROFIT |
3. What Renters Insurance Actually Covers (Beyond the Apartment)
Many apartment tenants skip renters insurance because they mistakenly believe: "I don't own fine jewelry or expensive antiques; my furniture is from IKEA."
However, renters insurance (HO-4 policy) provides three distinct structural protections:
Coverage C: Personal Property (World-Wide Protection): If someone smashes your car window and steals your backpack, laptop, and camera gear, auto insurance will repair the car window, but will reject the stolen electronics. Your renters insurance covers the stolen items even though the theft occurred away from your apartment.
Coverage D: Loss of Use / Additional Living Expenses: If a kitchen grease fire in a neighboring apartment renders your building uninhabitable for 6 weeks, your landlord is not required to pay for your temporary housing. Renters insurance pays for your hotel room, restaurant food stipends, and storage units.
Coverage E: Personal Liability ($100k to $300k): If a guest trips over a rug in your living room and fractures an elbow, or if your bathtub accidentally overflows and destroys the drywall of the tenant living below you, renters liability pays the damages and legal defense costs.
4. How to Execute the Bundle with Your Current Insurer
1. Log into your current auto insurance mobile application (e.g., Progressive, GEICO, State Farm, Allstate).
2. Click "Add a Policy" or "Get a Renters Quote."
3. Select $20,000 or $30,000 in Personal Property coverage with a $500 deductible.
4. Select $100,000 or $300,000 in Personal Liability.
5. Review the new monthly payment: the multi-policy auto discount should automatically apply to your auto declarations page.
Compare Verified Rates in Your State
Benchmark rate filings from Progressive, State Farm, GEICO, Allstate, and Travelers with zero obligation.
Frequently Asked Questions
Q: Does my landlord need to be named on my renters insurance policy?
Many property management companies require you to list them as an "Interested Party" or "Additional Certificate Holder." This simply ensures the insurer notifies the landlord that your required liability coverage is active.
Q: Can roommates share one renters insurance policy?
While some carriers allow unrelated roommates to share a policy, it is generally discouraged. If your roommate files a claim, it goes on your permanent CLUE insurance record for 5 years. It is cleaner and cheaper for each roommate to hold their own $12/month policy.
Q: Does renters insurance cover flood damage?
No. Just like homeowners insurance, renters insurance excludes natural floodwaters and rising groundwater. If you live in a ground-floor or basement rental unit in a flood zone, you should purchase an inexpensive FEMA NFIP renters contents policy.
Related Authority Insurance Guides
Gap Insurance Explained: When Is It Worth It?
Learn how gap insurance covers vehicle loan depreciation deficits for $30/year.
Limits BaselineHow Much Car Insurance Do I Actually Need?
Why state minimums put your savings at risk and why 100/300/100 is baseline.
Bundling SecretsHome & Auto Bundling: Save 25% on Premiums
Compare multi-line discount tiers across State Farm, Allstate, and Progressive.