Key Takeaways at a Glance
- The Asset Protection Gap: Standard auto liability ($250k) and homeowners liability ($300k) leave everything above those limits vulnerable to court garnishment.
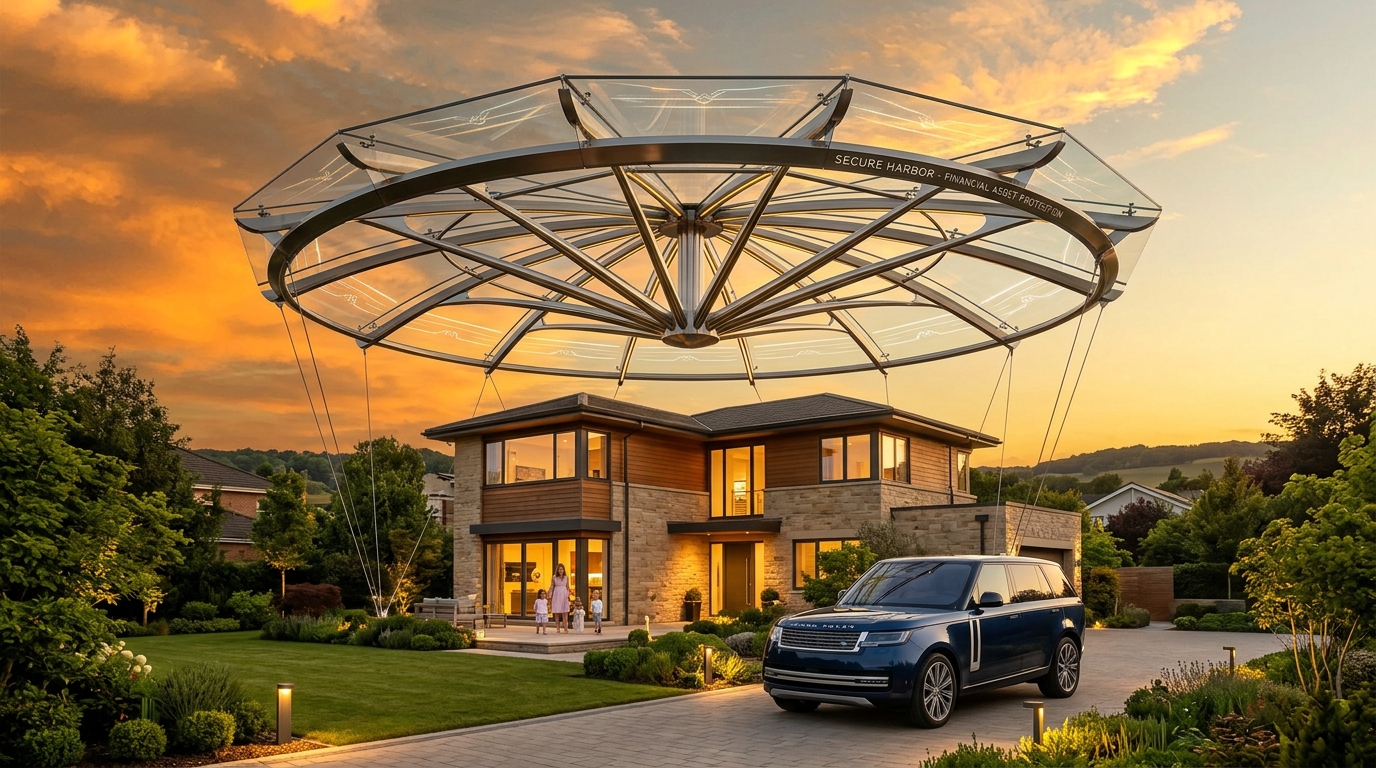
- Excess Coverage Architecture: A Personal Umbrella Policy (PUP) provides an extra $1,000,000 to $5,000,000 in liability protection that floats over both home and auto.
- Astonishing Affordability: Because umbrella policies only trigger during catastrophic high-dollar lawsuits, a $1 Million policy costs only $150 to $250 per year (~$15/month).
- Worldwide Protection: Umbrella coverage includes international travel liability, defense attorney legal costs outside policy limits, and false arrest or slander defense.
1. The Wealth Myth: Umbrella Insurance Is Not Just for Millionaires
A pervasive myth in consumer finance is that "umbrella insurance is only for the ultra-wealthy." In reality, high-net-worth individuals have legal trusts and LLC structures to shelter their assets. The people most vulnerable to financial devastation from a major lawsuit are middle-class families with a home, retirement savings, and future wage earnings.
Consider an everyday scenario: Your 17-year-old child looks down at a text message while driving on the highway, hydroplanes, and causes a multi-vehicle collision that permanently disables an orthopedic surgeon. Medical bills, lost future income, and pain-and-suffering judgments easily exceed $1.8 Million.
If your auto policy caps bodily injury liability at $250,000 per person and $500,000 per accident, you are personally liable for the remaining $1.3 Million deficit. Under state legal judgments, courts can force the liquidation of your non-retirement brokerage accounts, place liens on your home equity, and garnish up to 25% of your disposable paycheck for the next 10 to 20 years.
2. How an Umbrella Policy Connects with Home & Auto
A Personal Umbrella Policy (PUP) does not operate as standalone insurance. Instead, it sits directly on top of your underlying primary Property & Casualty policies:
To qualify for an umbrella policy, your primary insurer requires you to maintain specific underlying baseline limits:
- Auto Bodily Injury: Minimum $250,000 per person / $500,000 per accident (or $300,000 combined single limit).
- Auto Property Damage: Minimum $100,000.
- Homeowners Personal Liability: Minimum $300,000 or $500,000.
When a catastrophic lawsuit exhausts your $250,000 auto limit or your $300,000 homeowners limit, your umbrella policy seamlessly triggers to pay the next $1,000,000, $2,000,000, or $5,000,000.
3. What Umbrella Covers vs What It Excludes
Umbrella insurance offers exceptionally broad liability definitions, including risks omitted by underlying policies:
| Covered by Personal Umbrella Policy | Excluded from Umbrella Policy |
|---|---|
| Catastrophic multi-car traffic crashes | Your own personal injuries (medical bills) |
| Dog bite claims exceeding homeowner limits | Intentional, criminal, or fraudulent acts |
| Swimming pool drownings and slip-and-fall incidents | Damage to your own personal home or belongings |
| Slander, libel, defamation, and false arrest | Business pursuits and professional malpractice (E&O) |
| Worldwide liability incidents while traveling abroad | Boats/watercraft over specific horsepower (unless endorsed) |
| Legal defense legal costs (outside policy limits) | Contractual business disputes or tenant evictions |
4. 6 Triggers That Make an Umbrella Policy Mandatory
1. You Own a Home with Substantial Equity: If your home has appreciated significantly, that equity represents low-hanging fruit in a post-judgment asset search.
2. You Have Teen or Young Adult Drivers in the Household: Statistically, drivers aged 16 to 24 have crash rates 3x higher than experienced drivers.
3. You Own High-Liability Property: Having an in-ground swimming pool, trampoline, hot tub, dock, or treehouse dramatically increases premise liability risk.
4. You Own Dogs (Especially Guard Breeds): Dog bite claims average over $58,000 per claim according to the Insurance Information Institute (III).
5. You Host Dinner Parties or Entertain Frequently: Social host liability laws hold homeowners responsible if an intoxicated guest causes a drunk driving crash after leaving your party.
6. You Coach Youth Sports or Serve on Non-Profit Boards: Extracurricular activities expose volunteers to personal injury and negligence claims.
5. The Best $200 You Will Ever Spend
A $1,000,000 umbrella policy typically costs between $150 and $250 annually. Increasing coverage to $2,000,000 usually adds only $75 to $100 more per year. Crucially, your umbrella policy pays for your defense attorney legal fees in addition to policy limits, meaning the insurer spends hundreds of thousands on top-tier legal defense without diminishing your $1 Million coverage.
Compare Verified Rates in Your State
Benchmark rate filings from Progressive, State Farm, GEICO, Allstate, and Travelers with zero obligation.
Frequently Asked Questions
Q: Can I buy an umbrella policy from a different insurance company?
Most carriers require you to maintain your auto and home insurance with them before they will issue an umbrella policy. However, standalone umbrella carriers (such as RLI or PersonalUmbrella.com) offer policies that wrap over disparate carriers.
Q: Are 401(k) and IRA retirement accounts protected from lawsuits without umbrella insurance?
Under federal ERISA law, employer-sponsored 401(k) and 403(b) plans have strong protection against civil lawsuit judgments. However, Traditional and Roth IRAs have varying protections under state law, making umbrella coverage critical.
Q: Does umbrella insurance cover lawsuits if someone slips on my icy sidewalk?
Yes. If a postal carrier or neighbor slips on your icy driveway or sidewalk, your homeowners liability covers the first $300,000, and your umbrella covers all damages above that up to your limit.
Related Authority Insurance Guides
Gap Insurance Explained: When Is It Worth It?
Learn how gap insurance covers vehicle loan depreciation deficits for $30/year.
Limits BaselineHow Much Car Insurance Do I Actually Need?
Why state minimums put your savings at risk and why 100/300/100 is baseline.
Bundling SecretsHome & Auto Bundling: Save 25% on Premiums
Compare multi-line discount tiers across State Farm, Allstate, and Progressive.