Key Takeaways at a Glance
- The Carfax Stigma: The moment a repaired vehicle receives an accident notation on Carfax or AutoCheck, its market trade-in resale value drops by 10% to 25%.
- Inherent Diminished Value: Under tort law in almost all states, you have the right to collect compensation from the at-fault driver’s insurance for this lost resale equity.
- The Georgia 17c Formula Trap: Insurance adjusters will try to calculate your claim using the infamous 17c formula, which caps payouts at arbitrary, deflated figures.
- Independent Certified Appraisal: Spending $250–$350 on an independent licensed appraisal is the single most effective way to recover a $3,000–$7,000 diminished value check.
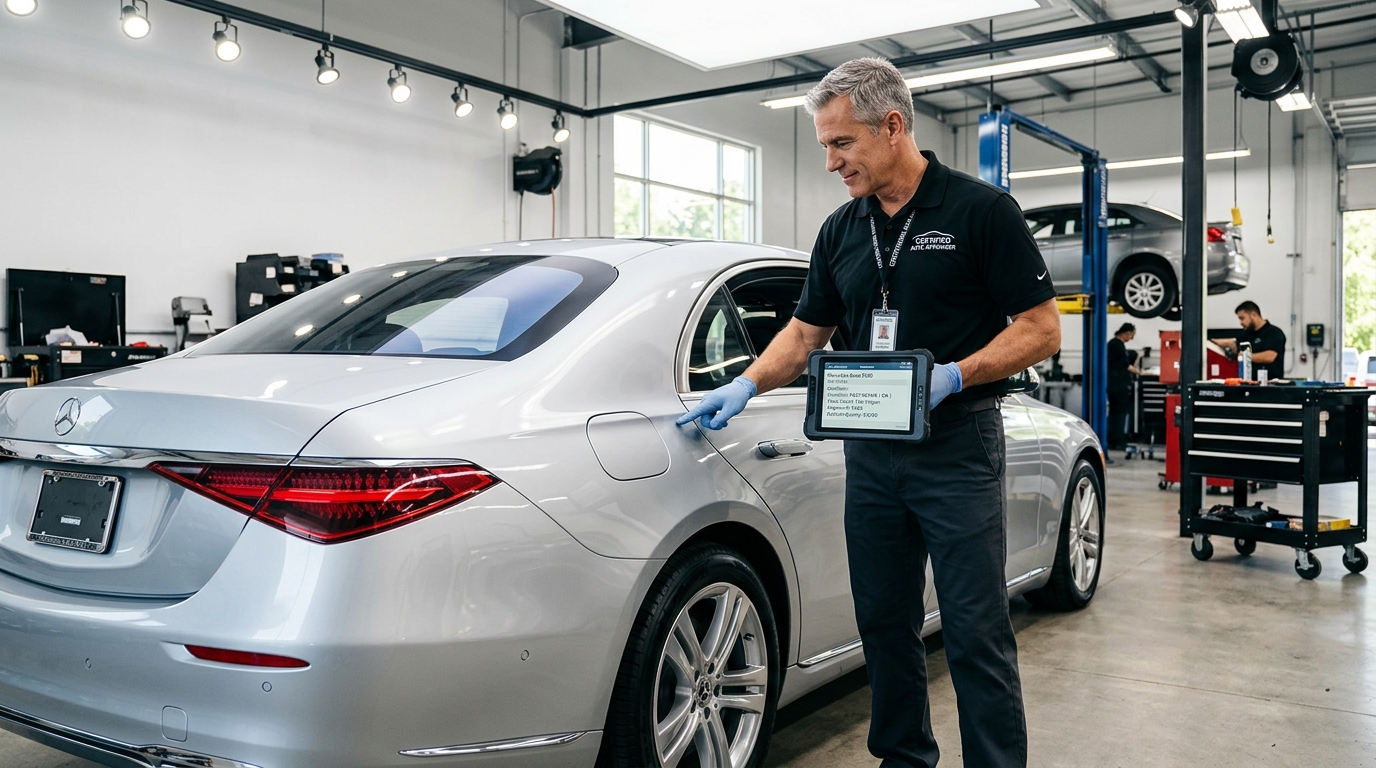
1. What Is Diminished Value & Why Are You Owed Money?
Imagine you own a pristine 2024 luxury SUV with 12,000 miles. You are stopped at a red light when an inattentive driver rear-ends you, causing $11,000 in bumper and frame damage.
The at-fault driver's insurance carrier pays the body shop directly, and your vehicle is repaired to industry factory specifications. You drive home feeling whole.
One year later, you visit a dealership to trade the vehicle in. The dealer runs a Carfax report, identifies the major structural accident record, and immediately deducts $5,500 from their trade-in offer. If two identical vehicles sit on a used car lot at the same price, no rational consumer will buy the one with an accident history. That loss in market value is called Inherent Diminished Value.
2. The 3 Types of Diminished Value
1. Inherent Diminished Value: The clean-loss market stigma that remains on the vehicle solely because of the accident history, assuming optimal professional repairs. This represents 90% of all successful claims.
2. Repair-Related Diminished Value: Loss in value resulting from substandard workmanship, such as mismatched paint hues, crooked body panel gaps, or aftermarket parts that rattle.
3. Immediate Diminished Value: The difference in vehicle resale value immediately prior to the crash versus immediately after the crash before any repairs occur (rarely used in practice).
3. Beware the "17c Formula": The Insurer’s Underpayment Trick
Originating from the 2001 Georgia Supreme Court case State Farm Mutual Automobile Insurance Co. v. Mabry, many national insurers attempt to use the "17c Formula" across other states to minimize claim payouts.
The 17c formula caps maximum diminished value at 10% of the vehicle’s pre-crash value, and then applies severe multiplying deductions for mileage and structural damage. Under 17c, an insurer might offer you an insulting $600 check for a luxury vehicle that actually suffered $4,500 in documented market loss.
Unless you live in Georgia (where 17c is standard case law), you are NOT legally bound by this internal formula. You are entitled to actual market loss based on real-world dealer trade-in comparisons.
4. Step-by-Step Playbook: How to Collect Your Settlement
Follow these steps once your body shop repairs are fully completed:
Step 1: Wait Until All Repairs Are Completed & Signed Off: Never discuss diminished value until you have physically picked up your vehicle and verified all bodywork is complete.
Step 2: Obtain 2 Dealer Trade-In Valuation Quotes: Take your car to two independent dealerships (like CarMax or a franchise dealer). Ask for an appraisal in writing and specifically ask the appraiser: "How much did you deduct because of the accident history on Carfax?"
Step 3: Hire an Independent Certified Diminished Value Appraiser: For vehicles worth over $20,000, spend $250 to $350 to hire an USPAP-compliant independent auto appraiser. They will pull real dealer auction loss data and produce a comprehensive 20-page evidence dossier.
Step 4: Send a Formal Demand Letter to the At-Fault Adjuster: Send the certified appraisal report alongside a formal demand letter via certified mail or secure email. Set a firm 14-day response deadline.
Step 5: Negotiate from Strength or Escalate to Small Claims: Insurers will typically counter-offer at 40% of your demanded amount. Hold firm using your certified appraisal. If they refuse to budge, filing a small claims lawsuit against the at-fault driver (whose insurer must defend them) frequently triggers an immediate full settlement.
5. State-by-State Rules: Third-Party vs First-Party Claims
Understanding who you can collect from based on your state:
| Claim Type | Eligible States | Legal Basis | Key Requirement |
|---|---|---|---|
| Third-Party Claim (At-Fault Driver's Insurer) | All 50 States | Common Law Tort Negligence | You must be 0% at fault (or meet comparative negligence bars). |
| First-Party Claim (Your Own Collision Policy) | Georgia Only (General rule) | Contractual Policy Language | Standard policies in 49 states explicitly exclude diminished value. |
| Uninsured Motorist (UMPD Diminished Value) | Select States (TX, VA, GA, WA, TN) | UMPD Statutory Mandate | Uninsured driver caused crash and was identified. |
Compare Verified Rates in Your State
Benchmark rate filings from Progressive, State Farm, GEICO, Allstate, and Travelers with zero obligation.
Frequently Asked Questions
Q: Can I file a diminished value claim if the accident was my fault?
No. Unless you live in Georgia, standard auto insurance contracts in 49 states specifically exclude first-party diminished value claims under your own collision policy.
Q: How long do I have to file a diminished value claim?
Statutes of limitations for property damage vary by state, typically ranging from 2 to 3 years from the date of the collision.
Q: Is diminished value worth pursuing on an older car?
Diminished value claims are generally only viable for vehicles that are less than 6 to 7 years old, have under 80,000 miles, had no prior accident history, and sustained at least $3,000 in repair damages.
Related Authority Insurance Guides
Gap Insurance Explained: When Is It Worth It?
Learn how gap insurance covers vehicle loan depreciation deficits for $30/year.
Limits BaselineHow Much Car Insurance Do I Actually Need?
Why state minimums put your savings at risk and why 100/300/100 is baseline.
Bundling SecretsHome & Auto Bundling: Save 25% on Premiums
Compare multi-line discount tiers across State Farm, Allstate, and Progressive.